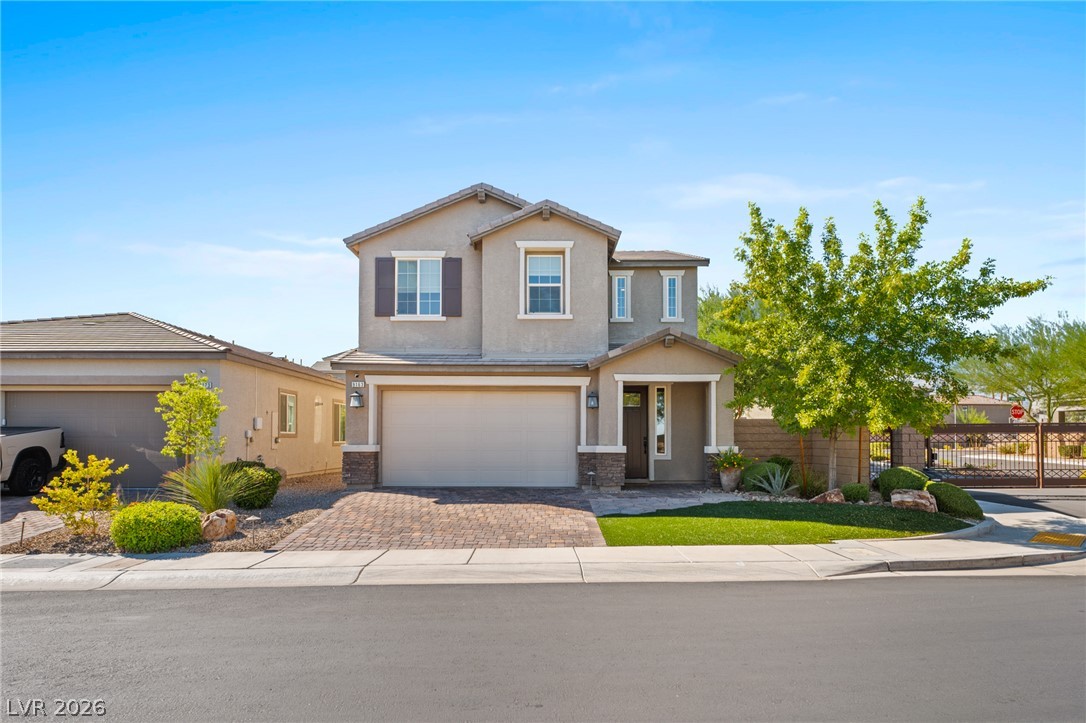
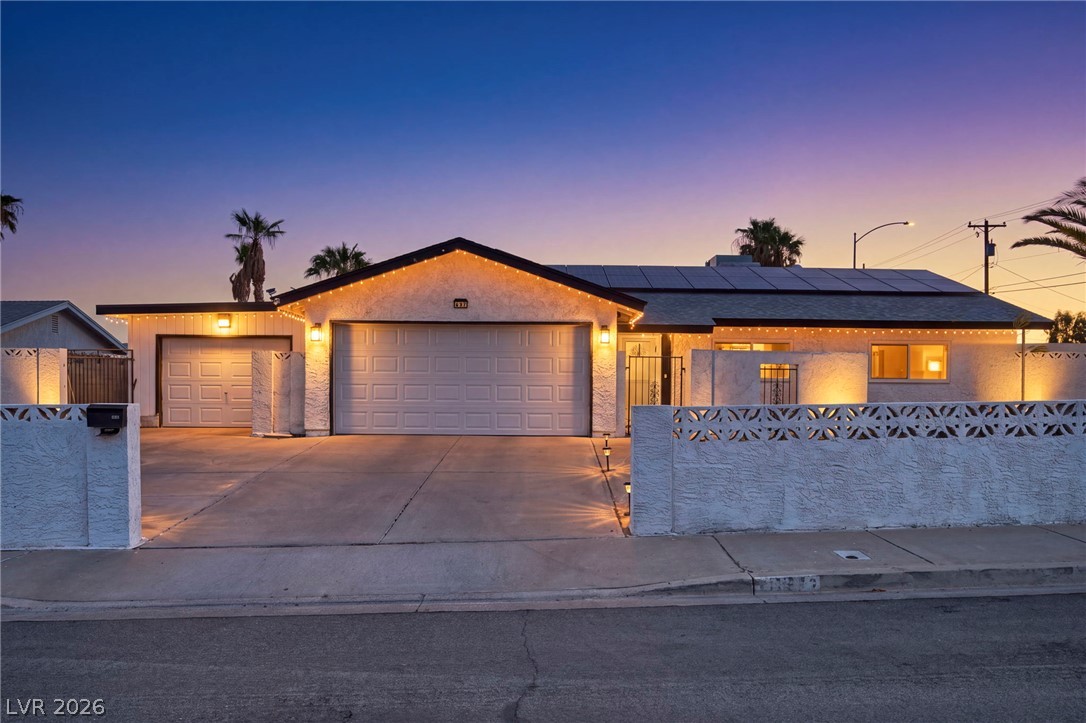
$515,000Listed today
3 bedrooms2 bathrooms1,650 square feet
637 Apollo Avenue, Henderson 89002
Wardley Real Estate
Highland HillsIDX MLS 2824860
Enter your income, debts, and down payment for an instant estimate of your buying power in Las Vegas.
Lenders look at two ratios: your housing payment against your income, and all your debts against your income. The lower one sets your limit.
The housing payment stays under 28% of your gross monthly income.
A rule of thumb, not a loan decision. A lender looks at your full picture and may approve more or less. Not a loan offer from VIPhomes.Vegas.
It finds the highest price whose full monthly payment fits under both lending ratios, then rounds down to the nearest $1,000.
It divides your yearly household income by 12.
The housing limit is 28 percent of that monthly income.
It works backward from that monthly number to a price, counting principal and interest on the loan, property tax, homeowners insurance, and HOA dues.
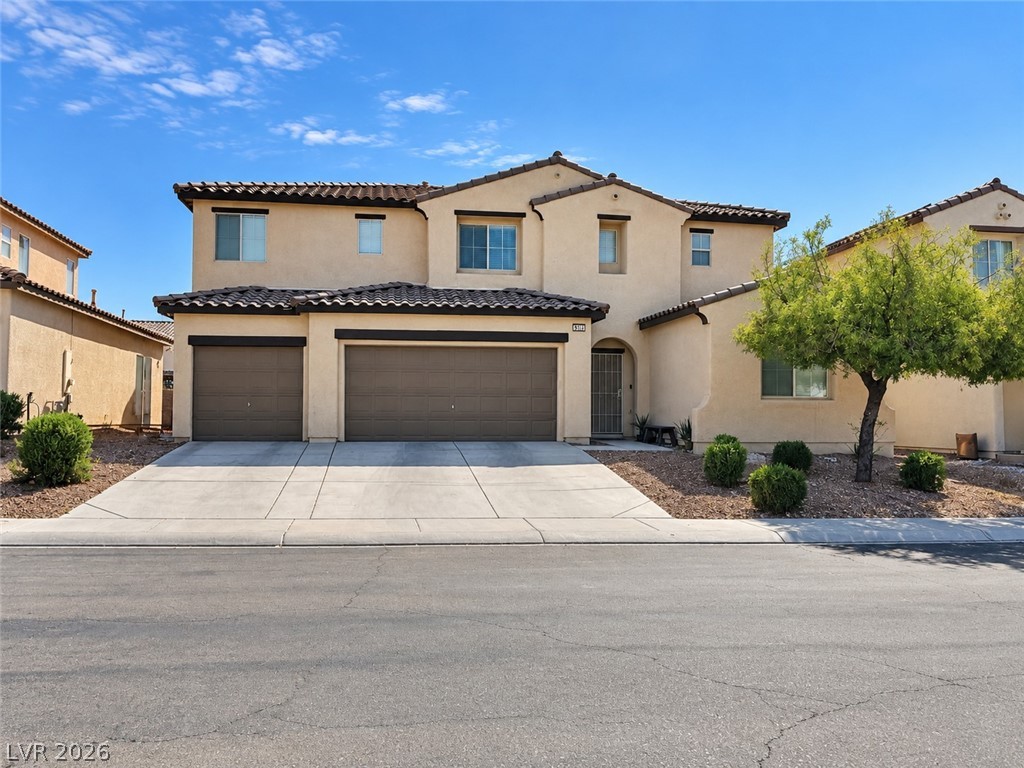
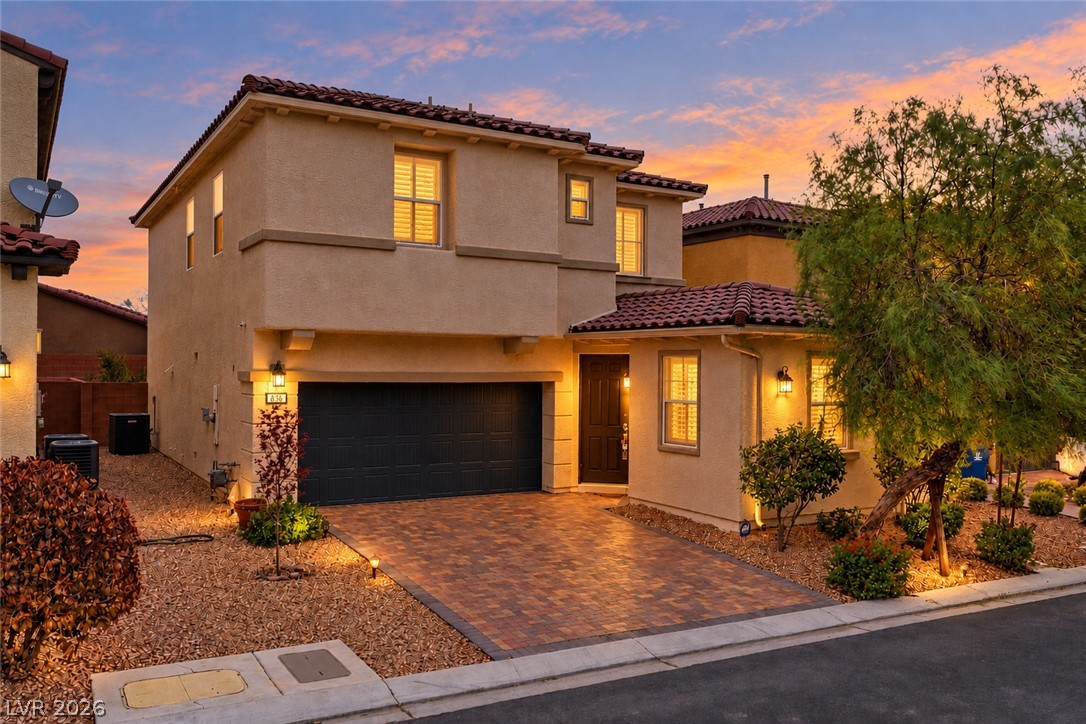
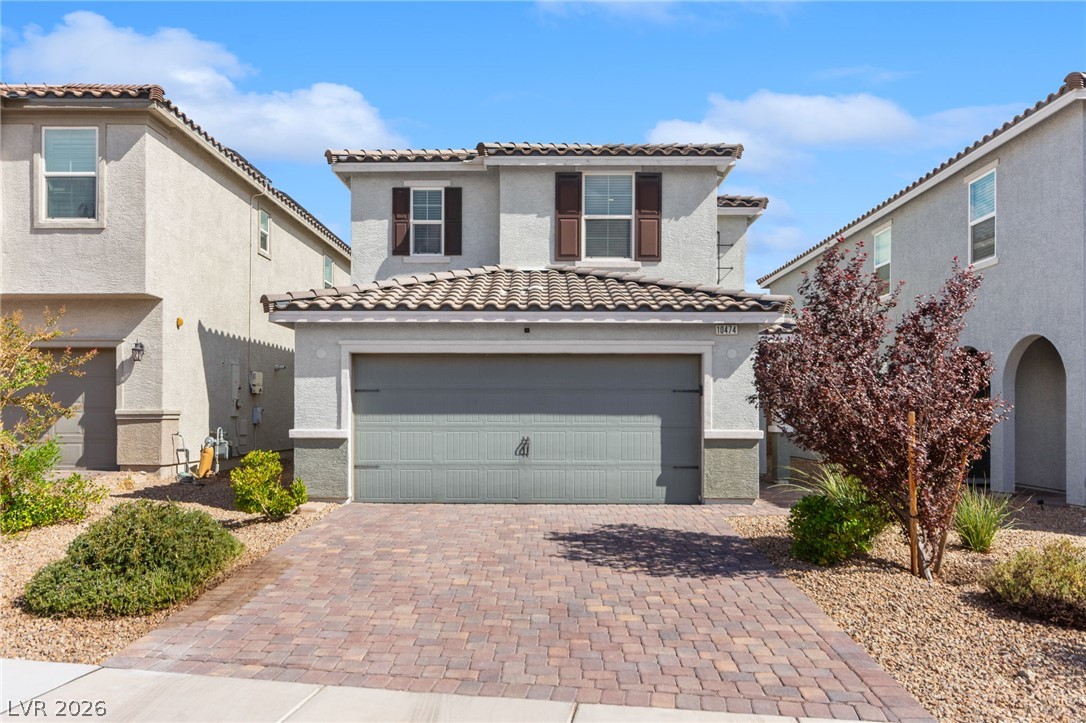
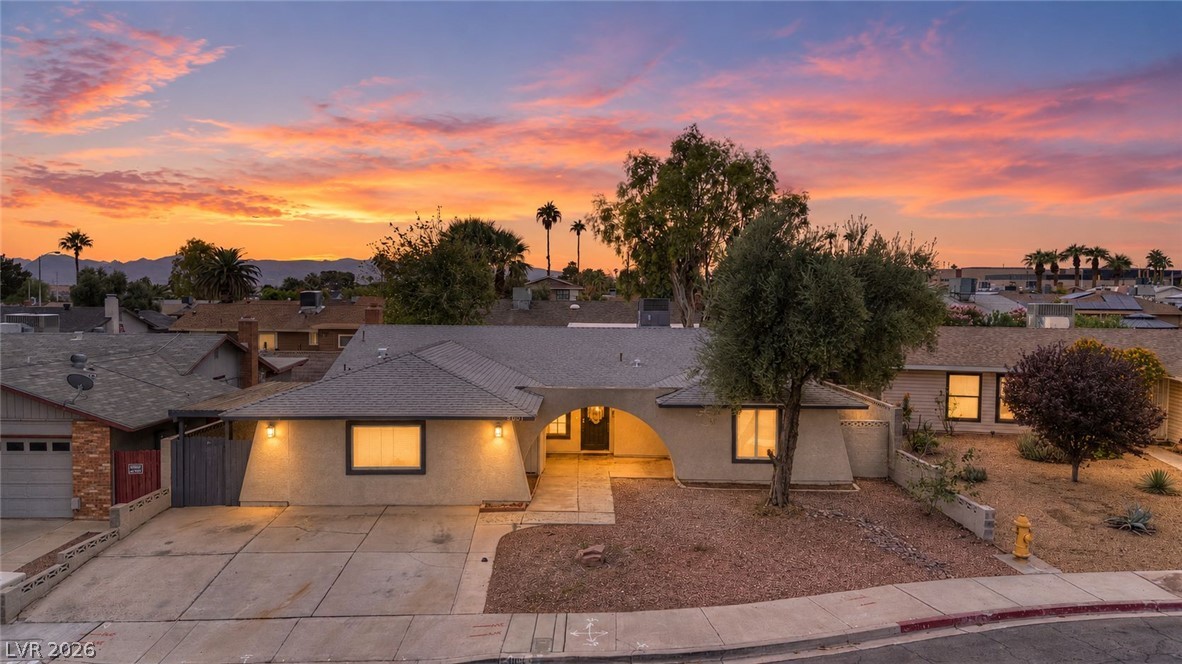
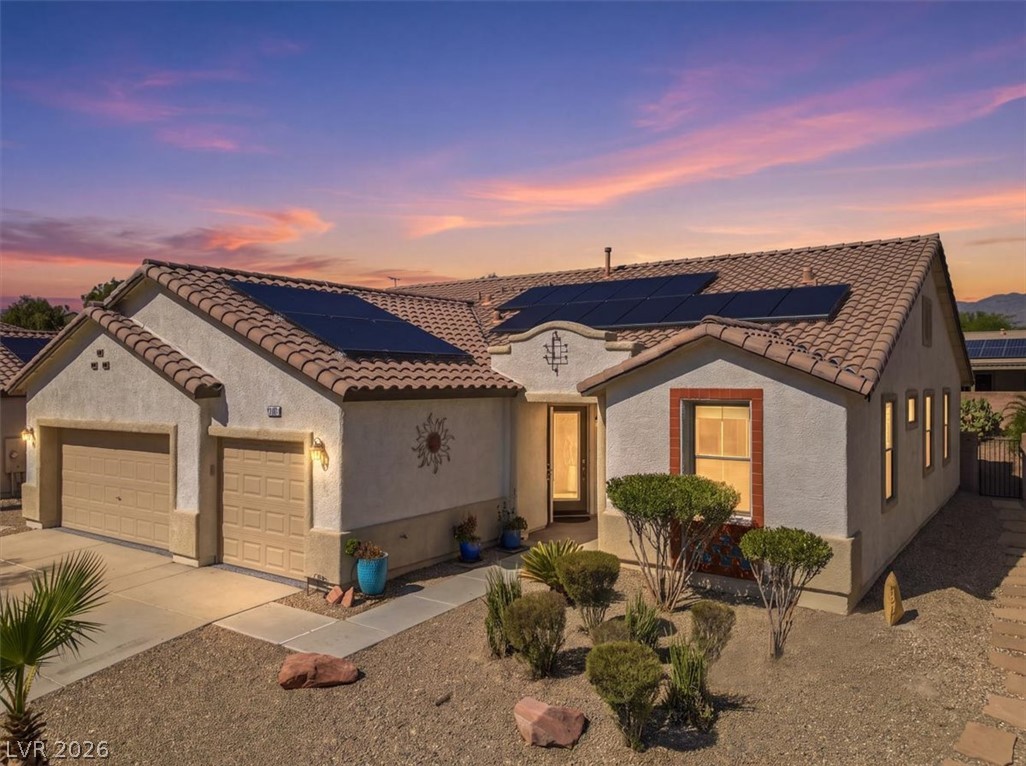
The newest Las Vegas homes listed between $450,000 and $530,000, with their real listing photos.
Wardley Real Estate
Signature Real Estate Group
Signature Real Estate Group
Simply Vegas
Huntington & Ellis, A Real Est
ERA Brokers Consolidated
Century Communities of Nevada
Keller Williams MarketPlace
Found one you like? Put its price and HOA dues in the calculator above for its real payment.
See homes up to $530KReal numbers come from a lender. Jeremy Day at Five Star Mortgage is the one we trust, and the introduction costs nothing.
Optional. You are free to use any lender.
Your rate, your other debts, and the costs that come with the home: HOA dues, insurance, and property tax.
Most Las Vegas neighborhoods have an HOA, and many master-planned communities have two: a master association and a neighborhood one.
Nevada's property tax is low compared with most states.
The starting number is $2,000 a year.
A point of interest rate moves your range by tens of thousands of dollars.
28 and 43 percent are a conservative rule of thumb.
Want the payment on one home? Mortgage insurance, taxes, and HOA dues in one number.
Run my paymentEach community has its own prices, HOA dues, and pace. These are the Las Vegas communities buyers ask us about most, with what is for sale there today.
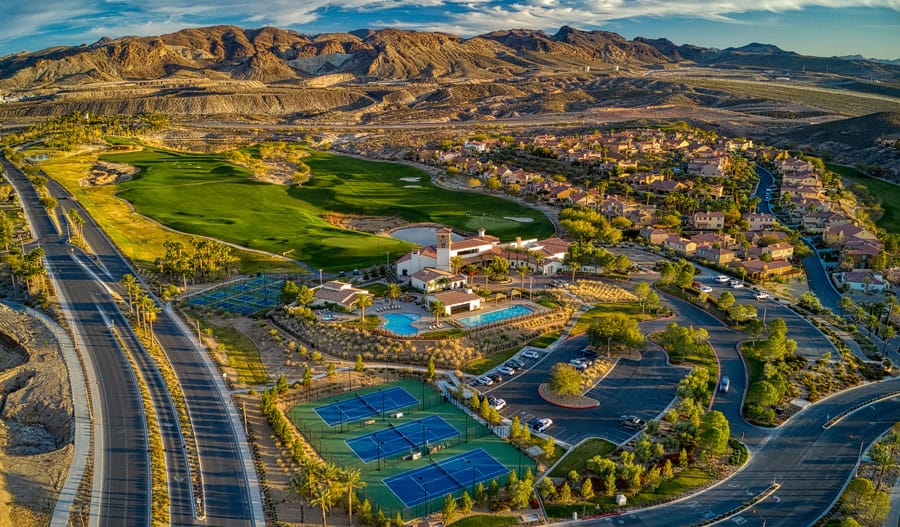 Homes inSouthern Highlands128 for sale$1000K median
 Homes inInspirada142 for sale$549K median
 Homes inAnthem221 for sale$660K median
 Homes inMountains Edge134 for sale$525K median
 Homes inSeven Hills63 for sale$825K median
 Homes inSummerlin979 for sale$700K median
 Homes inRed Rock Country Club
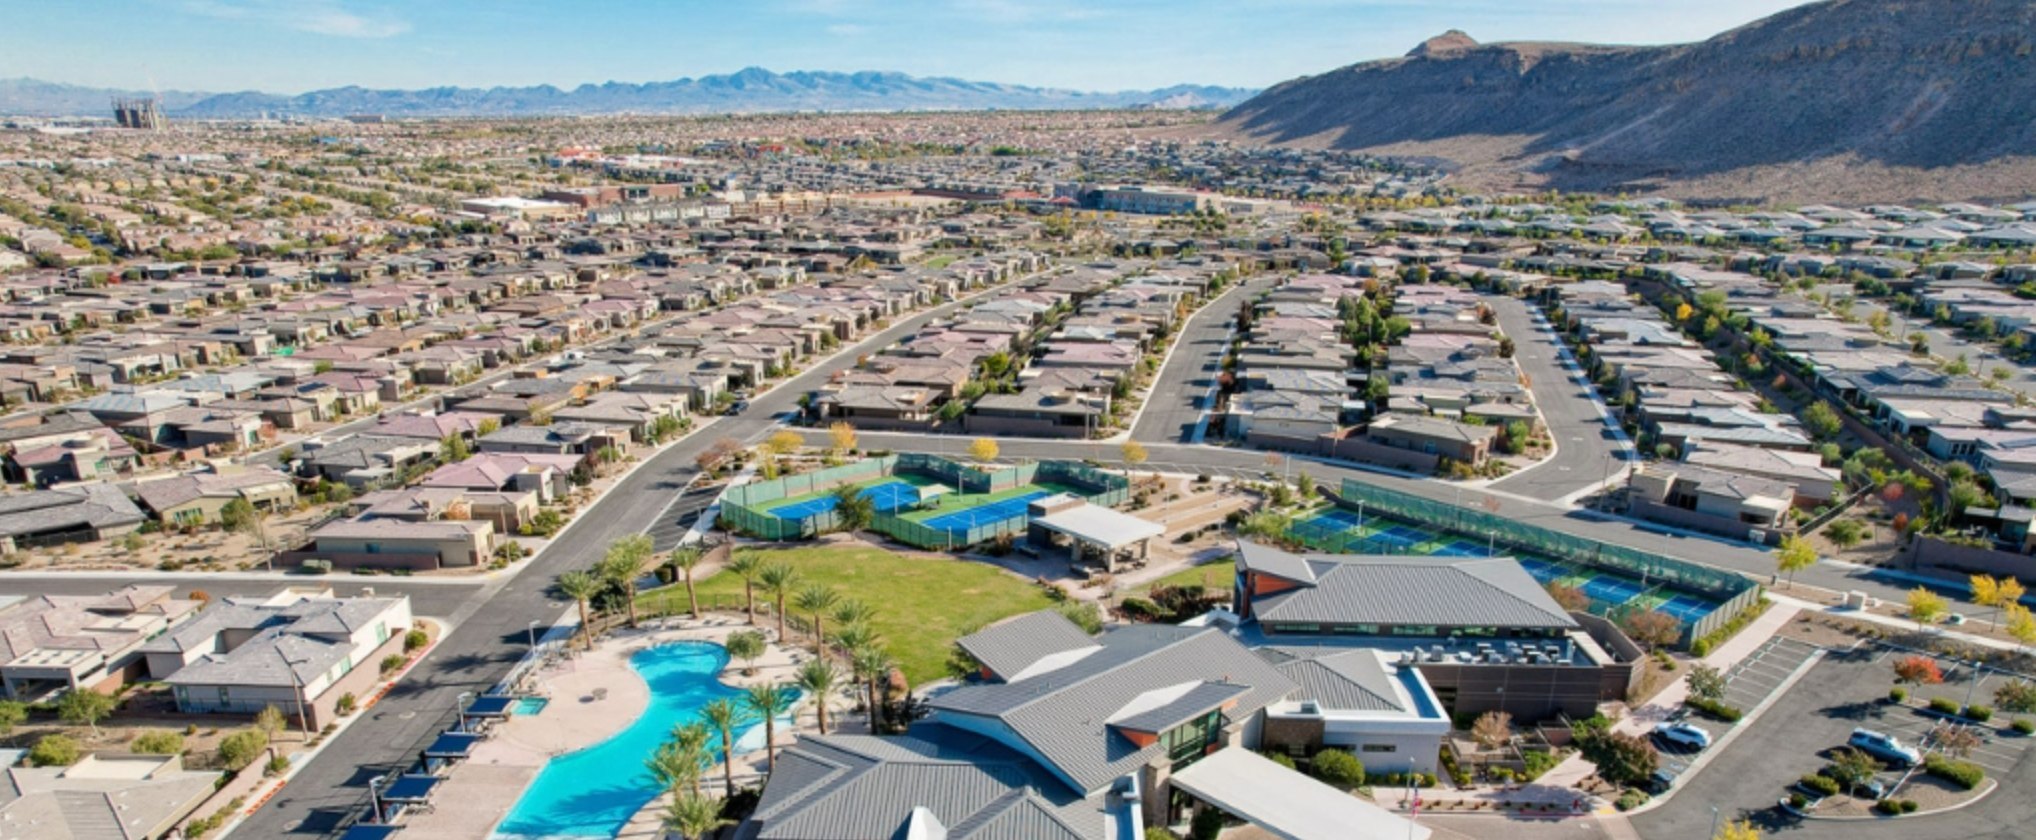 Homes inRegency in Summerlin
Not sure where to start? Compare every community side by side.
Compare communitiesMy husband and I spent a day touring homes with Truman Fleming last week. We are looking to relocate from CA and we did not have a lot of information about the…
As first time homeowners, I'm glad we trusted Truman Flemming to help us buy our dream home.
Truman made every a super easy process and we were able to close extremely fast. Thankful for Truman and his team on making it happen
Truman Fleming is a very personable and professional Realtor. He took us on as client, knowing that we needed to find a house right away in a rough market.
From our very first meeting, Truman was incredibly thorough. Selling a home is a complex, often overwhelming process, but he took the time to break down every…
Ready to start your search? Tell us what you want and we line up the homes.
Talk to Truman Read every reviewWith the calculator's starting assumptions, $500 in monthly debts, and $40,000 down, about $340,000. Your rate, debts, down payment, and HOA dues change that, so put in your own numbers above.
A lending rule of thumb: your housing payment stays at or under 28 percent of gross monthly income, and all your monthly debts, including the new housing payment, stay under 43 percent.
No. It includes principal and interest, property tax, insurance, and HOA dues. With less than 20 percent down on a conventional loan, mortgage insurance adds to the payment, so your range will be a bit lower.
Often, yes. Many lenders approve total debt ratios above 43 percent, up to 50 percent on some conventional loans. Being approved for more does not mean the payment will feel comfortable, so look at both numbers.
Gross income, before taxes. Lenders use gross income for their ratios, and so does the calculator.
It depends on the loan. Some conventional loans allow 3 percent down, FHA allows 3.5 percent, and VA loans can be zero down for eligible buyers. Twenty percent down on a conventional loan avoids mortgage insurance. You also need cash for closing costs.
Get pre-approved. A lender checks your income, credit, and assets and gives you a real number, which also makes your offers stronger.
It finds the highest price whose full monthly payment fits under both lending ratios, then rounds down to the nearest $1,000.
With the starting numbers, $150,000 a year is $12,500 a month. The housing limit is $3,500 and the debt limit is $4,875, so housing sets the limit. With $60,000 down at 6.5 percent over 30 years, that buys a home of about $529,000, with a monthly payment just under $3,500.
The calculator does not add mortgage insurance. If you put less than 20 percent down on a conventional loan, or use an FHA loan, your real limit will be somewhat lower. The mortgage calculator shows a payment with mortgage insurance included.
Your rate, your other debts, and the costs that come with the home: HOA dues, insurance, and property tax.
Tell us what you are after and we will reply the same day with real answers, not a drip campaign.